The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
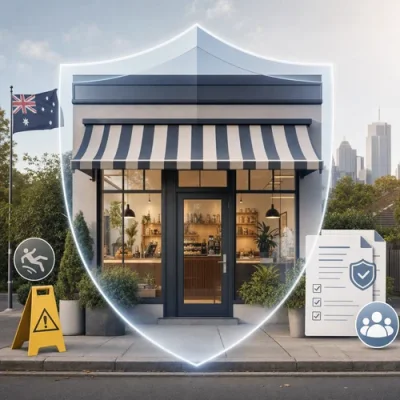
Small businesses can face liability claims from customers, clients, employees, products, advice, services and day-to-day operations. This guide explains common liability risks in Australia, how insurance can form part of a risk management strategy, and practical steps that may help business owners assess, document and manage those risks.
Why liability risk matters for small businesses
Liability risk is the possibility that a business may be held responsible for injury, property damage, financial loss or other harm connected with its activities. For a small business, a single incident can involve legal costs, compensation claims, investigation time, damaged relationships and disruption to normal operations.
Insurance is one way businesses can transfer some of this financial risk, but it is not the only risk management tool. Sound procedures, staff training, clear documentation, safe premises, careful contract management and regular reviews all help reduce the chance of an incident becoming a claim.
This article is general information only. Insurance needs vary by business type, industry, contracts, customers and risk profile, so policy wording, exclusions, limits and conditions should be reviewed carefully before relying on any cover.
Common liability risks Australian small businesses should understand
Different businesses face different exposures. A cafe, consultant, trades business, online retailer and manufacturer may all need to think about liability differently. The following table summarises major categories discussed in this guide.
| Risk area |
What can give rise to a claim |
Insurance commonly considered |
| Public liability |
A member of the public, customer, supplier or visitor alleges injury or property damage arising from business activities. |
Public liability insurance. |
| Product liability |
A product manufactured, distributed or sold by the business allegedly causes injury, damage or loss. |
Product liability insurance, sometimes considered alongside public liability arrangements. |
| Professional advice or services |
A client alleges negligence, error, omission, breach of duty or advice that caused financial or reputational loss. |
Professional indemnity insurance. |
| Employee-related injuries or illness |
An employee is injured or becomes ill in connection with their work. |
Workers compensation and workplace risk management arrangements. |
| Cyber and data events |
A data breach, cyberattack or system incident causes financial, operational or reputational harm. |
Cyber liability cover may be considered where relevant. |
Public liability risk
Public liability risk arises when third parties interact with your business. This may include customers on your premises, visitors to a worksite, suppliers attending a location, or members of the public affected by your business activities.
Examples can include a customer slipping in a shop, property damage caused while providing a service, or an incident at a business event. Public liability insurance is designed to respond to certain third-party injury or property damage claims, including associated legal costs and compensation where the policy applies.
When reviewing public liability arrangements, businesses commonly consider the nature of their work, where services are performed, the number and type of people they interact with, contract requirements and the level of cover needed for plausible claim scenarios. For a deeper policy-focused guide, see how to choose the right public liability insurance for your business.
If you are assessing possible cover levels, a tool such as the Public Liability Insurance Calculator may help frame the discussion, although it should not replace reading the policy or seeking professional guidance.
Product liability risk
Product liability risk is relevant to businesses that manufacture, import, distribute, supply or sell products. If a product defect or failure is alleged to have caused harm, the business may face investigation costs, legal fees, compensation claims and reputational damage.
Product-related risk management may include supplier checks, quality control, clear instructions, batch records, safety warnings, complaint handling and product recall procedures where applicable. Insurance can help respond to covered claims, but prevention and traceable records remain important.
Professional indemnity risk
Professional indemnity risk is especially important for businesses that provide advice, designs, recommendations, consulting, technical services or professional expertise. A claim may arise if a client alleges that an error, omission, negligent advice or breach of professional duty caused loss.
Consultants, accountants, architects and other service-based businesses are examples of operations that may need to consider this exposure. Professional indemnity insurance can help with covered compensation claims and legal defence costs, subject to the policy terms.
Because professional indemnity policies can differ in how they respond to claims, businesses should pay close attention to definitions, exclusions, notification requirements and the period of cover. For more detail, see professional indemnity insurance in Australia.
Employee-related and workplace liability risks
Small businesses have obligations to provide a safe working environment. Workplace incidents may involve injuries, illness, lost wages, medical costs and disruption to the business. The source of the risk may be physical hazards, unsafe systems of work, inadequate training, poor supervision or equipment issues.
Workers compensation is a key consideration for employee injuries or illnesses connected with work. Insurance should be supported by practical workplace safety measures, including induction, role-specific training, hazard reporting, incident recording, regular safety checks and updated procedures.
Cyber liability and data-related risk
Cyber liability is increasingly relevant because small businesses often rely on digital systems, customer records, online payments, email and cloud services. A data breach or cyberattack can create financial and reputational consequences, as well as operational disruption.
Risk management may include access controls, staff awareness, secure record handling, software updates, backup processes and clear procedures for responding to suspected breaches. Cyber liability insurance may be considered as part of the overall insurance program where the exposure is relevant to the business.
How to assess your business vulnerability
A risk assessment helps identify where liability claims could realistically arise. It does not need to be complicated, but it should be structured and revisited as the business changes.
- List your main activities, locations, products, services and customer interactions.
- Identify who could be affected, including customers, clients, employees, contractors, suppliers and the public.
- Consider what could go wrong, such as slips, damaged property, faulty products, incorrect advice, unsafe work practices or data incidents.
- Review the likelihood and potential severity of each scenario.
- Check current controls, such as training, maintenance, documentation, contracts, supervision and insurance.
- Prioritise improvements and assign responsibility for follow-up.
Common scenarios can vary widely. A cafe might consider burns from hot drinks or slips on wet flooring. A marketing consultant might consider advice that a client says caused financial loss. A trades business might consider property damage during work at a customer site. The aim is to connect realistic exposures with practical controls and suitable insurance options.
Insurance as part of a broader risk management strategy
Insurance can protect against some financial consequences of liability claims, but it does not remove the need to manage the underlying risk. A claim may still involve excesses, exclusions, time, business disruption and reputational pressure.
When comparing insurance policies and providers, it is important to review more than the premium. Consider the type of cover, policy limits, exclusions, conditions, excesses, the claims process and how well the policy fits the business activities. Businesses that want to compare available options can start with liability insurance quotes and information and then review policy documents carefully.
The appropriate level of cover depends on factors such as business size, industry, premises, customer base, contracts, products, services and plausible worst-case claim scenarios. Some businesses also consult an insurance broker or risk management adviser for help interpreting policy options and matching cover to business risks. You can also read more about the role of brokers.
Insurance should be reviewed when the business changes. New premises, new products, larger contracts, additional staff, different services or changed customer interactions can all affect liability exposure.
Legal obligations and compliance
Managing liability risk also requires awareness of the legal and regulatory environment that applies to the business. Australian businesses may need to consider workplace health and safety, consumer protection, employment arrangements, contracts and industry-specific obligations.
The original source article identified legislation such as the Competition and Consumer Act 2010 and the Work Health and Safety Act 2011 as examples of legal frameworks that may be relevant. The exact obligations depend on the business and its sector, so owners should stay informed about legal changes affecting their industry.
Legal counsel can assist with business structures, contract reviews, employment practices and compliance questions. Legal advice can also be important where an incident has occurred or a claim is threatened.
Creating a culture of safety and awareness
Risk management is more effective when it becomes part of everyday operations rather than a one-off exercise. Employees should understand the risks connected with their role and know what to do if something goes wrong.
- Train employees in safe handling of products, equipment and customer interactions.
- Encourage staff to report hazards before they become incidents.
- Use written procedures for recurring tasks and higher-risk activities.
- Review incidents and near misses to identify improvements.
- Keep safety protocols up to date as work practices, premises or services change.
- Conduct refresher training where procedures or risks have changed.
Documentation supports this culture. Training records, maintenance logs, inspection checklists, incident reports and customer communications can all help demonstrate the steps taken to manage risk.
What to do when an incident occurs
Prompt, organised action can help protect people, preserve evidence and support the claims process. The following steps are general and may need to be adapted to the circumstances.
- Address immediate safety concerns and take reasonable steps to prevent further harm.
- Arrange medical or emergency assistance where required.
- Record what happened while details are fresh.
- Take photographs of the area, equipment, product or damage where appropriate.
- Collect names and contact details of witnesses.
- Preserve relevant records, such as emails, contracts, CCTV footage, maintenance logs and incident reports.
- Notify the insurer as soon as possible and follow the policy's claims instructions.
- Keep a log of claim-related communications, including dates, names and summaries of conversations.
Insurers will generally guide policyholders through the next steps, which may include completing claim forms, providing further evidence and responding to information requests. Clear records can help the insurer assess the matter and can assist if the business needs to defend its position.
Key takeaways
- Small business liability risk can arise from public interactions, products, professional services, employees, cyber events and compliance issues.
- Public liability, product liability, professional indemnity, workers compensation and cyber liability cover may each be relevant depending on the business.
- Insurance is only one part of risk management; procedures, training, documentation and safety controls are also important.
- Policy limits, exclusions, conditions and claims processes should be reviewed carefully.
- Regular reviews help keep risk management aligned with changes in business activities, contracts, staff, premises and customer interactions.
Understanding liability risk helps small business owners make more informed decisions about prevention, insurance and claims preparation. The right approach is usually a combination of practical controls, accurate records, legal and compliance awareness, and insurance that reflects the business's actual exposures.
Published: Tuesday, 10th Sep 2024
Author: Paige Estritori


No comments yet. Be the first to share your thoughts.