


Liability Insurance :: News
SHARE

Share this news item!

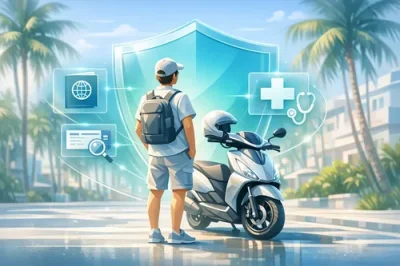
Scooter Accidents Put Travel Insurance Fine Print Back in Focus

Licence rules, helmets and activity exclusions can make a major difference

Scooter Accidents Put Travel Insurance Fine Print Back in Focus?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

Recent consumer attention on scooter and moped accidents overseas has highlighted a travel risk many Australians underestimate until something goes wrong.
Hiring a scooter in Bali, Thailand, Vietnam or parts of Europe can feel like a simple holiday convenience, but insurers may treat it very differently from catching a taxi or joining a tour.

The issue is not only whether a policy includes overseas medical cover. Many travel insurance policies apply specific conditions to riding motorcycles, mopeds, scooters or similar vehicles. These can include holding the correct Australian and local licence, wearing a helmet, staying within engine-size limits, obeying road rules and not riding under the influence of alcohol or drugs. If those conditions are not met, a medical or liability claim may be reduced or declined.

For Australian travellers, the financial stakes can be significant. A seemingly minor crash can involve ambulance transport, emergency treatment, surgery, hospital admission, new flights, extra accommodation and help from family members. Where a passenger is injured, or another road user is involved, personal liability questions may also arise. In countries where medical providers expect upfront payment or guarantee of payment, the right cover and emergency assistance access can be critical.

This is also a reminder that cheap travel insurance is not always suitable for a trip with higher-risk activities. Before hiring any vehicle overseas, travellers should check:

  • whether scooters, mopeds or motorcycles are covered automatically or only through an optional add-on;
  • the maximum engine capacity allowed under the policy;
  • whether the traveller needs an Australian motorcycle licence, an international driving permit or a local permit;
  • whether pillion passengers are covered;
  • helmet, alcohol, drug and road-rule exclusions;
  • what evidence may be needed if a claim is made, such as rental paperwork, police reports and medical records.

Timing also matters. Buying cover after an accident, injury, destination disruption or medical issue has already occurred will not usually fix the problem. Broader factors such as government travel advice can also influence how a claim is assessed, particularly where travellers ignore warnings or proceed after a risk becomes known.

The practical lesson is to match the policy to the holiday, not just the destination. If scooters, adventure activities, nightlife, remote areas or long stays are part of the plan, travellers should compare travel insurance options with those details in mind. Reading the Product Disclosure Statement and Target Market Determination before departure is far easier than trying to interpret exclusions from a hospital bed overseas.

Published:Wednesday, 2nd Sep 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Insurance News

What Electric Heavy Vehicles Mean for Truck Insurance
10 Sep 2026: Paige Estritori
Recent transport and fleet industry coverage continues to point to a steady increase in electric and low-emission heavy vehicles across Australian logistics operations. For many operators, the attraction is clear: quieter vehicles, lower tailpipe emissions, potential fuel savings and stronger alignment with customer sustainability targets. But the insurance conversation is now becoming more detailed than simply replacing a diesel truck with an electric one. - read more
Why the Latest Insurance Data Matters for Trade Businesses
10 Sep 2026: Paige Estritori
APRA’s latest quarterly general insurance statistics point to a market that is still under cost pressure, even as insurers continue to report stronger overall results than during the worst of the recent claims cycle. For Australian tradespeople, the headline is not simply whether insurers are profitable. The practical issue is how rising premiums, repair costs, reinsurance expenses and claims activity flow through to the price and availability of cover used every day on the tools. - read more
Advice Changes Could Make Income Cover Easier to Understand
10 Sep 2026: Paige Estritori
Australia’s financial advice reform agenda has taken another important step, with industry attention turning to how simpler, more accessible guidance could help consumers make better decisions about insurance. For workers who rely on income insurance or salary continuance cover, the issue is more practical than political: many people hold cover they do not fully understand until illness or injury forces them to test it. - read more
Why Battery Freight Is Becoming a Truck Insurance Issue
10 Sep 2026: Paige Estritori
Recent transport and insurance industry attention on lithium-ion battery safety is a timely warning for Australian truck operators. The issue is no longer limited to consumer products catching fire in homes or warehouses. Batteries now move through freight networks in tools, scooters, e-bikes, electronics, spare parts and energy storage equipment, and that creates a different risk profile for carriers, depots and subcontracted linehaul work. - read more


Business Insurance Articles

Professional Indemnity Insurance in Australia: What It Covers and How It Works
Professional indemnity insurance can help protect Australian professionals and service businesses against claims arising from alleged errors, omissions, negligence or breaches of professional duty. This guide explains what it may cover, how claims-made policies work and what to check before arranging cover. - read more
The Importance of Documentation in Public Liability Claims
Public liability insurance is designed to help protect a business when it is found legally responsible for injury or property damage suffered by a third party because of its operations. If an incident occurs, the quality of your documentation can make a major difference to how clearly the claim is assessed. - read more
Product Liability Insurance in Australia: A Practical Guide for Business Owners
Product liability insurance can help protect Australian businesses from the financial impact of claims alleging that a product they manufactured, imported, distributed or sold caused injury, illness or property damage. This guide explains how the cover works, what to check in a policy and how it fits into broader product risk management. - read more
The Cost of Being Uninsured: Why Every Australian Small Business Needs Liability Coverage
Welcome to the complex world of running a small business in Australia where navigating through liability risks is as crucial as managing daily operations. This article is crafted to illuminate why every Australian small business needs liability coverage — a shield to protect against potential financial catastrophes. - read more


Start Here !
Start here!
Cover Amount:
Postcode:

All quotes are provided obligation-free by a participating broker from our national referral partner network. We respect your Privacy.


Knowledgebase
Incontestability Clause:
A provision in a life insurance policy that prevents the insurer from voiding coverage due to a misstatement by the insured after a certain period.