The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
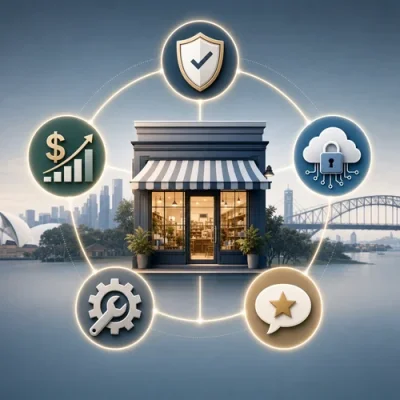
Running a small business can be rewarding, but it also means dealing with risks that can affect cash flow, operations, customers and reputation. Understanding the main risk areas can help business owners plan ahead, reduce avoidable exposure and consider where insurance may fit within a broader risk management approach.
Why small business risk management matters
Small businesses often have less capacity than larger organisations to absorb financial shocks, operational delays or legal disputes. A supplier issue, a customer injury, a cyber incident or a short interruption to trading can quickly affect revenue, staff, customers and business continuity.
Risk management is not about removing every possible problem. It is about identifying realistic exposures, reducing preventable risks and preparing a response if something goes wrong. The right mix of planning, documentation, compliance, staff training and insurance can help a business respond more effectively to unexpected events.
Quick overview: five common small business risks
| Risk area |
What it can involve |
Common management steps |
| Financial uncertainty |
Cash flow gaps, economic changes, unexpected expenses or lower demand |
Budgeting, cash reserves, forecasting, audits and diversified revenue streams |
| Legal liability |
Claims involving injury, property damage, products, services or business activities |
Compliance reviews, clear contracts, safe work practices and liability insurance considerations |
| Cybersecurity threats |
Data breaches, phishing, ransomware or system compromise |
Staff training, strong passwords, multi-factor authentication, software updates and response planning |
| Operational disruption |
Floods, fires, storms, power outages, supply chain failures or labour issues |
Business continuity planning, emergency procedures, communication plans and backup systems |
| Reputational damage |
Negative customer experiences, failed products, disputes or public criticism |
Customer service processes, transparent communication, review monitoring and prompt issue handling |
Risk 1: Financial uncertainty
Financial uncertainty is one of the most common challenges for small businesses. Cash inflows may not always align with expenses such as wages, rent, stock, supplier invoices or equipment costs. Sudden changes in market demand or broader economic conditions can also affect sales and profitability.
Practical financial controls can reduce the chance that a short-term setback becomes a major problem. Useful steps include:
- building and maintaining a realistic operating budget;
- keeping a cash reserve where possible for unexpected expenses;
- monitoring revenue and expenses regularly rather than only at tax time;
- using cash flow forecasting to identify likely shortfalls early;
- conducting periodic financial reviews or audits; and
- considering whether the business is too dependent on a single product, service, supplier or customer group.
Insurance may also form part of a financial risk strategy. Depending on the policy, business insurance can help address certain losses linked to events such as property damage, liability claims or interruption to trading. Policy terms, exclusions, limits and excesses vary, so cover should be reviewed carefully before relying on it as part of a risk plan.
Risk 2: Legal liability
Legal liability risks arise when a business is alleged to have caused injury, property damage or another loss through its premises, products, services or activities. For example, a customer or supplier might be injured at a business location, or damage might occur while work is being carried out.
Public liability risk is especially relevant for many small businesses that interact with customers, suppliers, contractors or members of the public. Public liability insurance is designed to respond to certain claims where the business is found liable for injury or damage, and may cover legal costs and compensation payments within the policy terms. Business owners can learn more about the broader concepts in understanding liability insurance for Australian small business owners.
Managing legal liability is not only about insurance. It also involves reducing the chance of an incident occurring in the first place. Common steps include:
- keeping premises and work areas reasonably safe;
- documenting procedures for staff, contractors and suppliers;
- reviewing contracts, terms of trade and customer communications;
- staying informed about compliance obligations relevant to the business and industry;
- keeping records of incidents, complaints and corrective actions; and
- seeking professional legal or insurance assistance where the business faces complex exposures.
When considering public liability cover, factors such as policy limits, exclusions, excesses and conditions can affect how a policy responds. The public liability insurance calculator may be a useful educational tool for thinking about public liability insurance needs, while further guidance on policy features is covered in how to choose the right public liability insurance for your business.
Risk 3: Cybersecurity threats
Many small businesses rely on technology for payments, customer records, bookings, emails, cloud systems, marketing and day-to-day administration. That reliance creates exposure to cyber threats such as phishing scams, data breaches, ransomware and unauthorised access to systems.
A cyber incident can affect finances, operations and reputation at the same time. For example, a business may need to notify affected customers, restore systems, respond to legal issues or manage a period of reduced trading while systems are unavailable.
Basic cyber risk management should be practical and consistent. Useful measures include:
- training employees to recognise suspicious emails, links and payment requests;
- using strong passwords and avoiding password sharing;
- enabling multi-factor authentication where available;
- regularly updating software, devices and systems to address known vulnerabilities;
- backing up important data; and
- having a response plan for suspected data breaches or system compromise.
Cyber liability insurance may also be considered as part of a broader risk plan. Depending on the policy, it can respond to costs associated with cyber incidents, such as legal fees, customer notification expenses and certain ransomware-related costs. As with any insurance, the detail of the policy wording determines what is and is not covered.
Risk 4: Operational disruption
Operational disruption occurs when a business cannot operate normally. Causes can include natural events such as floods, fires and storms, as well as human-made or infrastructure-related events such as power outages, supplier failures, transport issues or labour disruptions.
Because small businesses often rely on a limited number of staff, suppliers, systems or locations, a single interruption can have a wide effect. A business continuity plan helps set out what the business will do before, during and after a disruption.
What to include in a continuity plan
- the most important business functions that need to be restored first;
- emergency response procedures for staff and customers;
- key supplier, landlord, insurer and professional adviser contact details;
- communication steps for customers, staff, contractors and suppliers;
- backup systems for records, payments and critical data;
- alternative working arrangements where practical; and
- a schedule for reviewing and updating the plan.
Business interruption insurance may assist with loss of income during periods when the business cannot operate as usual due to an insured event. However, this type of cover is subject to policy terms and should be considered alongside practical continuity measures rather than as a substitute for them.
Risk 5: Reputational damage
Reputation is important for small businesses because customer trust, repeat work and referrals can be central to ongoing revenue. A negative incident, poor customer service experience, product problem or public dispute can affect how customers, suppliers and partners view the business.
Reputational risk can also overlap with other risk areas. A liability incident, cyber breach or operational failure may create reputational consequences if customers believe the business has responded poorly or failed to communicate clearly.
Businesses can reduce reputational risk by focusing on consistent conduct and prompt issue handling. Practical steps include:
- delivering on advertised promises and service standards;
- responding to complaints professionally and in a timely way;
- monitoring online reviews and social media comments where customers discuss the business;
- communicating transparently when something goes wrong;
- documenting customer issues and how they were resolved; and
- maintaining community or corporate responsibility activities where appropriate for the business.
Insurance does not prevent reputational damage, but liability cover may help with certain insured incidents that carry legal and financial consequences. The business still needs clear communication, good records and a practical plan for restoring customer confidence after a problem.
How insurance fits into a small business risk plan
Insurance is one part of risk management, not the whole strategy. It can provide financial support for specified events, but it usually works alongside prevention, compliance, documentation, training and business planning.
Common insurance considerations mentioned in this guide include:
- public liability insurance for certain injury or property damage claims involving third parties;
- business interruption insurance for loss of income during certain insured disruptions;
- cyber liability insurance for specified cyber incident costs; and
- property or other business insurance where physical assets or business operations are exposed to insured events.
Before choosing or relying on any policy, business owners should review the wording, limits, exclusions, excesses and conditions. Where insurance needs are complex, professional assistance from insurance brokers may help business owners understand available policy structures and questions to ask.
A practical small business risk review checklist
A regular risk review can help keep planning current as the business changes. The following steps provide a simple structure:
- List key risks: identify financial, legal, cyber, operational and reputational exposures that are realistic for the business.
- Assess likelihood and impact: consider how often each risk might occur and how serious the consequences could be.
- Prioritise actions: address high-impact and preventable risks first.
- Document controls: record procedures, responsibilities, training and reporting steps.
- Review compliance: check whether industry obligations, contracts or operating conditions have changed.
- Test continuity arrangements: make sure backup systems, emergency contacts and communication plans are usable.
- Review insurance: compare current cover against the business's activities, assets and potential liabilities.
- Update regularly: revisit the plan when the business grows, adds services, changes premises, hires staff or uses new technology.
Risk is an unavoidable part of running a small business. By identifying the main exposures and preparing practical responses, business owners can make more informed decisions about prevention, continuity planning and insurance.
Published: Wednesday, 30th Apr 2025
Author: Paige Estritori




No comments yet. Be the first to share your thoughts.