The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Public liability insurance can help protect a business when a third party alleges they were injured or their property was damaged because of the business's activities. If an incident occurs, knowing what to document, when to contact your insurer and how to communicate with others involved can make the claims process easier to manage.
What public liability insurance is designed to cover
Public liability insurance is intended to respond to certain third-party claims arising from business activities. A third party may be a customer, visitor, event attendee, property owner or another member of the public who alleges they suffered injury or property damage connected with your business operations.
Depending on the policy wording and the circumstances of the incident, cover may include legal costs and compensation payments if the business is found legally responsible. Common examples include a customer slipping and falling in a store, an attendee being injured by faulty seating at an event, or property being damaged while work is being carried out.
Public liability insurance is not unlimited. Common exclusions or limitations can include injuries to you as the business owner, injuries to employees, professional negligence, deliberate damage, incidents involving motor vehicles, and matters that fall outside the policy's public liability section. Always check your policy wording, limits, excesses and conditions carefully. For more background on policy selection issues, see this guide to choosing public liability insurance for your business.
Why the claims process matters
A public liability claim can involve several parties, including the business, the injured person or property owner, witnesses, the insurer, claims staff, assessors and sometimes legal representatives. Understanding the process helps you know what information may be needed and reduces the risk of avoidable delays or misunderstandings.
The process usually focuses on three broad questions:
- What happened?
- Was the business legally responsible under the policy circumstances?
- What loss, injury or damage has been claimed?
Preparation does not guarantee that a claim will be accepted or settled in a particular way. It does, however, help ensure your insurer has clearer information to assess the incident.
The public liability insurance claims process
Each insurer may manage claims differently, but the process often follows a similar pattern.
- An incident occurs. Someone alleges injury or property damage connected with your premises, work or business activities.
- The area is made safe. Immediate hazards should be controlled to reduce the risk of further injury or damage.
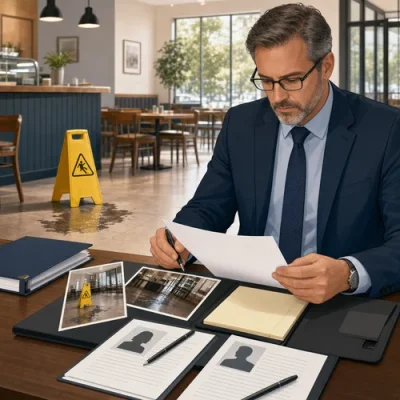
- Evidence is collected. This may include photos, videos, witness details, written notes, maintenance records or official reports.
- The insurer is notified. The incident should be reported as soon as reasonably practical, with your policy number and a factual summary.
- The insurer reviews the notification. The insurer may request more information, appoint a claims representative or involve an assessor.
- Liability and policy response are assessed. The insurer considers the facts, policy wording, exclusions and any claimed loss or damage.
- A decision or settlement process follows. If the claim is accepted, the insurer may negotiate or pay an amount in line with the policy and the assessed liability. If there is disagreement, dispute processes may be available.
Immediate steps after an incident
Make the area safe
The first priority is safety. Depending on the situation, this may involve cordoning off the area, arranging medical assistance, cleaning a spill, removing an obstacle, displaying warnings or stopping an activity until the risk is controlled.
These steps are important for the people involved and may also help demonstrate that the business responded responsibly once it became aware of the hazard.
Record what happened
As soon as it is safe to do so, record the facts while they are still fresh. Keep notes factual and avoid speculation. Useful details may include:
- the date, time and location of the incident;
- the names and contact details of people involved;
- what activity was taking place at the time;
- the condition of the area, including lighting, weather or obstacles;
- any immediate action taken after the incident;
- the names and contact details of witnesses; and
- the staff member or business representative who handled the incident.
Collect visual evidence
Photos and videos can help show the scene as it was at the time. Capture multiple angles, including the wider area and any specific hazard or damaged property. If the incident occurred outdoors, record any relevant weather or ground conditions. If equipment, flooring, signage or furniture was involved, photograph it before it is moved or repaired where safe and practical.
Notify your insurer
Contact your insurance provider as soon as feasible. Have your policy number ready and provide a concise, factual summary. The insurer may give instructions about what to provide next and whether any further steps should be taken before repairs, communication or settlement discussions occur.
Documents and evidence that may be needed
The strength and clarity of a claim file often depend on the quality of documentation. A more detailed guide to documentation in public liability claims may also be useful if you are reviewing your internal procedures.
| Information or document |
Why it may be relevant |
| Incident report |
Creates a factual record of what was reported, when it occurred and who was involved. |
| Photos or videos |
Shows the scene, property damage, conditions and possible contributing factors. |
| Witness statements or contact details |
Provides independent accounts that may support or clarify the sequence of events. |
| Maintenance records |
May show whether premises, equipment or fixtures were inspected, maintained or repaired. |
| Safety procedures and training records |
May help demonstrate risk management practices in place before the incident. |
| Official reports |
Police, paramedic or other official reports may be relevant where they were involved. |
| Correspondence |
Creates a record of communication with the insurer, claimant, property owner or other parties. |
| Quotes, invoices or medical bills |
May be used to assess the amount of claimed loss, repair cost or injury-related expense. |
Keep copies of all documents in one organised file. Record phone conversations in writing, including the date, time, person spoken to and key points discussed.
Communicating with third parties
How you communicate after an incident can affect the tone of the claim and the insurer's ability to manage it. It is usually appropriate to be calm, respectful and empathetic, especially where someone has been injured or property has been damaged.
At the same time, avoid admitting fault, speculating about causes or making promises about payment or claim outcomes. You can acknowledge that the incident occurred, explain that it is being reviewed and advise that your insurer has been or will be notified.
Professional communication also helps protect the reputation of the business. Keep public statements measured and accurate, and ensure staff know who is authorised to speak about the incident.
What a claims adjuster or assessor may do
A claims adjuster or assessor may be appointed by the insurer to help evaluate the claim. Their role can include inspecting the site, reviewing documents, assessing damage or injury information, asking questions and helping the insurer determine how the policy responds.
Before any visit or assessment, prepare the documents already collected, including incident reports, photos, witness details, maintenance records and relevant correspondence. If there are repair estimates, medical bills or other financial records related to the incident, keep those available as well.
During the assessment, answer questions factually and avoid guessing. If you do not know an answer, say so and offer to check records where possible. Cooperation is important, but it is also sensible to keep your own notes of what was discussed and what additional information was requested.
Subrogation and why it can matter
Subrogation refers to the insurer's ability, in some circumstances, to step into the insured party's position and seek recovery from another party responsible for the loss. This can arise where another person or business contributed to the incident.
Because subrogation rights may be affected by what you say or agree to after an incident, avoid signing releases, accepting responsibility or making private settlement arrangements without your insurer's guidance. If another contractor, supplier, property owner or service provider may have been involved, record the details and pass them to your insurer.
If you disagree with a claim decision
Disputes may arise if a claim is denied, the settlement amount is disputed or there is concern about how the claim has been handled. If this occurs, start by carefully reviewing the insurer's reasons and comparing them with your policy wording and the evidence you provided.
If you believe information has been missed or misunderstood, gather the relevant documents and present them clearly. This might include additional photos, witness statements, expert reports, repair information or correspondence.
Most insurers have internal dispute resolution processes. A written appeal or complaint should explain the issue, identify the outcome you are seeking and attach supporting evidence. Keep the tone professional and meet any timeframes specified by the insurer.
If the internal process does not resolve the matter, external assistance may be available through financial services ombudsman services or regulatory bodies. In complex or high-value disputes, legal advice may also be appropriate. You may also wish to learn more about the role of brokers and professional insurance assistance when reviewing how your cover is arranged and managed.
How to prepare before a claim ever happens
Have an incident response procedure
A written procedure helps staff know what to do when an incident occurs. It may cover who makes the area safe, who records details, who contacts the insurer and where documents are stored.
Maintain safety protocols
Risk management procedures should reflect the specific activities of the business. Examples may include regular premises inspections, safe work practices, equipment maintenance, warning signs and clear reporting lines for hazards.
Train staff and update records
Employees should understand common hazards, emergency response steps and incident reporting requirements. Training records, safety updates and inspection records may become relevant if a claim is later assessed.
Review your insurance regularly
Business activities can change over time. New services, different premises, larger contracts, events, subcontractors or changes in customer interaction may affect your insurance needs. Reviewing policy limits, excesses, exclusions and conditions can help identify whether your cover still reflects your operations. A public liability insurance calculator may help you think through cover levels as part of that review, although policy decisions should be based on your circumstances and policy advice where needed.
Key takeaways
- Public liability claims usually involve third-party injury or property damage connected with business activities.
- After an incident, prioritise safety, record the facts and notify your insurer promptly.
- Photos, witness details, incident reports, maintenance records and correspondence can all be important.
- Communicate respectfully, but avoid admitting liability or promising outcomes.
- Claims adjusters assess facts, policy response and supporting evidence.
- If you dispute a decision, use the insurer's dispute process and provide clear supporting documentation.
- Regular safety reviews, staff training and policy reviews can help a business prepare for future incidents.
If you are reviewing your current cover or comparing public liability insurance options, you can start an insurance enquiry through the website's quote-start page. Any review should consider your business activities, risks, policy wording and the level of cover required.
Published: Wednesday, 12th Jun 2024
Author: Paige Estritori



No comments yet. Be the first to share your thoughts.