The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
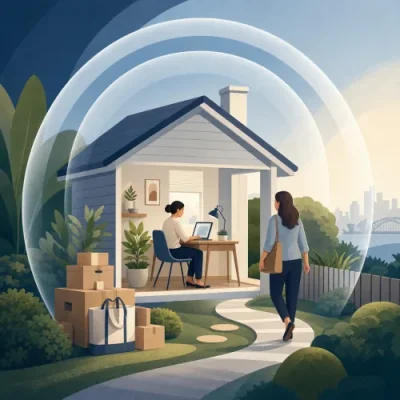
Home-based businesses can still face liability risks, even without a shopfront or commercial premises. This guide explains when liability insurance may be relevant, how home insurance can differ from business cover, and what risks Australian sole traders, freelancers and microbusiness owners should consider.
Do home-based businesses need liability insurance?
A home-based business in Australia does not automatically need the same insurance as a shop, clinic, workshop or office. However, working from home does not remove business liability risk. If clients visit your home, you visit client sites, sell products, provide professional advice or store business stock at home, you may still face claims connected with injury, property damage, defective products, professional mistakes or other business activities.
Liability insurance for home-based businesses is designed to help manage certain legal and financial risks that may arise from operating a business. Whether you need it depends on what you do, who you deal with, your contracts, your occupation, your premises arrangements and your insurer’s policy terms. For a broader overview of available cover types, see liability insurance information for Australian businesses.
This article provides general information only. It does not consider your personal objectives, financial situation or business needs, and it is not a substitute for reading a policy document or seeking professional advice where needed.
Why personal home insurance may not be enough
A common mistake is assuming that a home and contents policy will automatically cover business activities carried out from home. Many personal home insurance policies are written for domestic use. They may exclude or limit cover for business equipment, customer visits, business stock, product storage, commercial deliveries or liability arising from running a business.
For example, a home contents policy may cover household items but not specialist tools, stock for resale or equipment used to earn business income. A personal liability section may respond to certain domestic incidents, but not to claims arising from business operations. The position depends on the wording of your policy, any optional extras you have selected and what you have disclosed to the insurer.
If you operate even a small side business from home, it is important to tell your insurer accurately what you do. Non-disclosure or inaccurate information can affect whether a claim is accepted. You may need a business insurance policy, an extension to your home policy, or separate liability cover depending on your circumstances and the provider’s criteria.
Common liability risks for home-based businesses
Home-based business risks vary widely. A graphic designer working remotely has a different exposure from a candle maker storing stock, a therapist seeing clients at home or a consultant visiting client premises. The following risks are common areas to review.
- Client or customer visits: If clients, suppliers or couriers enter your home for business reasons, there may be a public liability exposure if someone is injured or their property is damaged.
- Business activities away from home: You may work from home but still attend client sites, markets, events, trade fairs or pop-up stalls. Incidents at those locations may not be covered by a personal home policy.
- Products sold from home: If you make, import, distribute or sell products, you may face product liability risk if a product allegedly causes injury, illness or property damage.
- Professional advice or services: Consultants, bookkeepers, designers, marketers, coaches and other service providers may face allegations involving errors, omissions, negligent advice or failure to deliver services as agreed.
- Stock and equipment stored at home: Stock, tools, packaging, devices and business records can create property and liability issues, especially if they increase fire, theft, trip or storage risks.
- Online services and data handling: A home office can still involve privacy, cyber and data-related risks if you store client information, process payments or use cloud systems.
- Staff, contractors or visitors: If other people work from or attend your home for business reasons, you may need to consider workplace health and safety, workers compensation and access risks.
Types of cover a home-based business may consider
There is no single policy that suits every home business. The relevant cover depends on the nature of your work and the risks you create for other people or property.
| Cover type |
What it may help with |
Home-based example |
| Public liability insurance |
Claims alleging injury or property damage suffered by a third party because of your business activities. |
A client trips while visiting your home office, or you damage a client’s property during an offsite appointment. |
| Professional indemnity insurance |
Claims alleging professional negligence, errors, omissions, misleading advice or breach of professional duty. |
A client alleges your advice, design, report or service caused them financial loss. |
| Product liability insurance |
Claims alleging a product you made, imported, supplied or sold caused injury, illness or property damage. |
A handmade product sold online or at a market is alleged to have caused harm. |
| Business property or portable equipment cover |
Loss or damage to business equipment, tools, stock or portable devices, subject to policy terms. |
A laptop, camera, tools or stock used for the business is stolen or damaged. |
| Cyber or data-related cover |
Certain costs connected with cyber incidents, privacy breaches or data loss, depending on the policy. |
A home-based consultant experiences a client data breach or business email compromise. |
Public liability and professional indemnity respond to different risks. If you are unsure how they differ, this guide to professional indemnity vs public liability insurance explains the distinction in more detail.
Home-based activities that can change your liability exposure
Clients or customers coming to your home
If people attend your home for appointments, classes, fittings, consultations, pick-ups or inspections, you should consider whether the premises are reasonably safe for business visitors. Risks may include uneven paths, stairs, pets, wet floors, poor lighting, parking hazards, unsecured equipment and access through private living areas.
Even occasional visits can matter. Some insurers may ask whether clients visit, how often they attend, which areas they access and whether the business has signage or dedicated premises space.
Storing stock, samples or equipment at home
Stock stored in a garage, spare room or shed may not be covered under standard contents insurance. It may also affect the risk profile of the property, particularly if the goods are flammable, valuable, fragile, temperature-sensitive or stored in large quantities. If you hold customer property, samples or hire equipment, ask how those items are treated under any relevant policy.
Selling products online or at markets
Many home businesses sell through websites, social media, online marketplaces or weekend markets. Product liability risk can apply even if you do not operate a physical shop. If you manufacture, label, repackage, import or distribute goods, check whether product liability is included in your public liability policy and whether any exclusions apply.
Markets, fairs and event organisers may also request a certificate of currency showing current public liability insurance before allowing you to trade.
Working from home but visiting other premises
Some home-based businesses have most of their administration at home but deliver services elsewhere. Examples include mobile beauty services, consultants, tutors, trades subcontractors, photographers and IT support providers. In these cases, the liability risk may arise at a client’s home, office, worksite or event venue rather than your own home.
Providing advice, designs or professional services
If clients rely on your expertise, your main risk may not be physical injury. It may be financial loss caused by alleged incorrect advice, a missed deadline, unsuitable recommendations, design errors, privacy failures or incomplete work. Professional indemnity insurance is often the cover businesses consider for these exposures, although availability, terms and pricing depend on the insurer and your occupation.
Rules and requirements to check before operating from home
Liability insurance is only one part of operating a home-based business. Depending on your situation, you may need to check other requirements before starting or expanding.
- Lease, mortgage, strata or body corporate rules: Renters, apartment owners and people in strata schemes may face restrictions on business use, signage, parking, customer visits, noise or storage.
- Council and planning rules: Local councils may have rules for home-based businesses, particularly where clients visit, goods are stored, food is prepared, traffic increases or the activity affects neighbours.
- Professional or industry requirements: Some occupations, licences, memberships or client contracts may require professional indemnity, public liability or other insurance.
- Market, event and supplier conditions: Stallholders and contractors are often asked to show evidence of public liability cover before participating.
- Employment and workplace obligations: If you employ staff, workers compensation and workplace health and safety obligations may apply. Requirements vary by state, territory and business structure.
For more detail on where insurance requirements can come from, see when liability insurance may be required for Australian businesses.
How to assess your home business liability insurance needs
A practical assessment starts with what your business actually does, not just where it operates. Consider the following questions:
- Who could be affected by your business? Think about clients, customers, couriers, suppliers, neighbours, landlords, contractors and members of the public.
- Where do business activities occur? Include your home, client sites, events, shared workspaces, vehicles, storage locations and online platforms.
- What could go wrong? List realistic scenarios such as injury, property damage, product defects, service errors, missed deadlines, data loss or damage to customer property.
- What do your contracts require? Review client agreements, lease conditions, platform terms, event applications and supplier contracts for insurance clauses.
- What does your current home policy exclude? Ask your home insurer how your business activities affect your home, contents and personal liability cover.
- How would a claim affect your finances? Consider legal defence costs, interruption to work, replacing equipment, refund demands and reputational impact.
- How might the business change? New products, higher revenue, staff, interstate sales, international customers or regular client visits can change the insurance picture.
Information to prepare before requesting quotes
If you decide to compare home based business liability insurance options, preparing accurate information can make the process smoother. Insurers and brokers may ask about:
- your occupation and exact business activities;
- whether clients, customers or suppliers visit your home;
- where you perform work outside the home;
- annual turnover or expected business income;
- products you make, import, sell or store;
- the value of business equipment, stock or customer property;
- whether you provide professional advice, designs or reports;
- contracts requiring specific insurance limits or certificates;
- previous claims, incidents or complaints; and
- risk controls, qualifications, licences and documented procedures.
Answer questions carefully and update your insurer if your activities change. A policy that suits a quiet home office may not suit a business that starts hosting clients, selling products at markets or storing higher-value stock.
Risk controls that may help reduce problems
Insurance does not replace sensible risk management. Home-based businesses can often reduce avoidable incidents by setting clear boundaries between domestic and business activities.
- Keep walkways, entry points and work areas clear and safe for visitors.
- Use secure storage for stock, tools, chemicals, samples and client property.
- Maintain records of client instructions, approvals, changes and delivered work.
- Use written terms of engagement, including scope, limitations and payment terms.
- Check product labelling, safety instructions and supplier documentation where relevant.
- Separate personal and business devices, accounts and records where practical.
- Back up business data and use appropriate security controls.
- Review council, lease, strata and insurer requirements before expanding.
- Keep certificates of currency and policy renewal dates organised.
Final Thoughts
A home-based business can still create liability exposure. The main question is not simply whether you work from home, but whether your business activities could cause injury, property damage, product-related harm, professional loss or other claims.
Personal home insurance may not cover business activities, so it is important to check your policy wording and disclose your business operations accurately. Public liability, professional indemnity, product liability, business property and cyber-related cover may all be relevant depending on what you do.
Before choosing cover, review your activities, contracts, property arrangements, council or strata rules and the people who interact with your business. Insurance availability, policy terms, limits and premiums depend on your individual circumstances and the insurer’s assessment criteria.
Published: Wednesday, 11th Nov 2026
Author: Paige Estritori


No comments yet. Be the first to share your thoughts.