Liability Insurance :: News
SHARE

Share this news item!

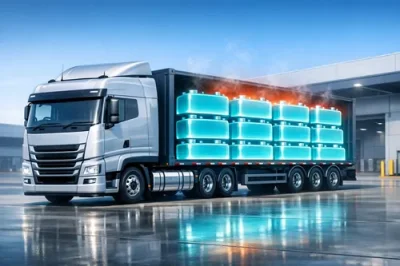
Why Battery Freight Is Becoming a Truck Insurance Issue

Small devices can create large exposure when cargo, compliance and downtime risks overlap

Why Battery Freight Is Becoming a Truck Insurance Issue?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

Recent transport and insurance industry attention on lithium-ion battery safety is a timely warning for Australian truck operators.
The issue is no longer limited to consumer products catching fire in homes or warehouses.
Batteries now move through freight networks in tools, scooters, e-bikes, electronics, spare parts and energy storage equipment, and that creates a different risk profile for carriers, depots and subcontracted linehaul work.

For insurers, the concern is not simply that a battery can ignite. The larger issue is how difficult a thermal runaway event can be to control once it starts, particularly inside a packed trailer, mixed-load pallet or depot environment. Smoke, heat, water damage and contamination can affect cargo that was not originally involved in the incident. A single load problem can therefore become a vehicle claim, a cargo claim, a liability question and a business interruption problem at the same time.

This is separate from, but connected to, the broader move towards battery-electric vehicles. Operators carrying battery-powered products need to think about the freight itself, not only the truck doing the work. Policies may treat lithium batteries differently depending on how they are packed, declared, charged, damaged, recycled or transported with other goods. Some policy wordings may also contain dangerous goods exclusions, special conditions or notification obligations that are easy to miss until a claim is lodged.

The practical starting point is documentation. Carriers should know what they are accepting, whether the consignor has classified the goods correctly, and whether packaging, labelling and handling procedures match the risk. Drivers and depot staff also need clear instructions on what to do if a package is swollen, hot, leaking, smoking or has been damaged in transit. Treating suspicious freight as an operational problem rather than an insurance problem can increase the eventual loss.

Operators should also review whether their existing truck policy, public liability arrangements and goods in transit or cargo cover respond in the way they expect. Key questions include whether fire damage to the truck is covered, whether customer goods are protected, whether clean-up costs are included, and whether subcontracting changes the position.

The insurance lesson is straightforward: as battery freight becomes more common, insurers will expect carriers to understand the exposure and manage it. Strong acceptance procedures, driver training, incident reporting and policy reviews can help reduce surprises when a battery-related loss turns into a complex claim.

Published:Thursday, 10th Sep 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Insurance News

Why rising builder failures matter for contract works cover
17 Sep 2026: Paige Estritori
Australia's construction sector remains under pressure, with recent insolvency figures continuing to show building and construction as one of the most exposed parts of the economy. Higher material costs, tight margins, labour shortages, delayed payments and fixed-price contract stress have all contributed to a tougher operating environment for builders, subcontractors and project owners. - read more
How Softer Truck Sales Can Affect Insurance Decisions
17 Sep 2026: Paige Estritori
Recent transport industry sales updates point to a more selective new-truck market, with operators weighing replacement timing against finance costs, emissions planning, availability and contract confidence. For truck businesses, that matters well beyond the showroom. A change in buying momentum can flow through to vehicle values, repair economics, insurer appetite and the way fleets should set insurance sums before renewal. - read more
Cyber Scam Alerts: What Trade Businesses Should Check Now
17 Sep 2026: Paige Estritori
Fresh small business cyber warnings are a practical reminder that digital risk is no longer just a concern for large companies with complex IT systems. For Australian tradespeople, the most damaging cyber incident may be far simpler: a fake invoice, altered bank details, a compromised email account or a scam message that looks like it came from a supplier, builder, real estate agent or client. - read more
Why Super Service Standards Matter for Your Income Protection
17 Sep 2026: Paige Estritori
ASIC’s continuing focus on superannuation member services has put another practical issue in front of Australian workers: insurance inside super is not just about whether cover exists, but whether members can understand and use it when they need help. Recent regulatory attention on trustee administration, communication and claims support is a timely reminder for anyone relying on salary continuance or income protection benefits through their fund. - read more


Business Insurance Articles

The Cost of Being Uninsured: Why Every Australian Small Business Needs Liability Coverage
Welcome to the complex world of running a small business in Australia where navigating through liability risks is as crucial as managing daily operations. This article is crafted to illuminate why every Australian small business needs liability coverage — a shield to protect against potential financial catastrophes. - read more
Public Liability Insurance Cost: Is It Worth It for Australian Businesses?
Public liability insurance is designed to help protect a business from the financial impact of third-party injury or property damage claims connected with its business activities. The cost varies by industry, risk profile and cover needs, so the value of a policy depends on how exposed your business is to the public, clients, contractors and property risks. - read more
Liability Insurance for Freelancers in Australia: What to Know
Freelancers can face liability risks when providing services, visiting client sites or working with client property. Liability insurance can help manage the financial impact of certain claims, but the right cover depends on the type of work you do, your contracts and your risk exposure. - read more
When Is Liability Insurance Required for Australian Businesses?
Liability insurance is not compulsory for every Australian business, but it may be required by law, licence conditions, contracts, leases, tenders, permits or client agreements. This guide explains where requirements commonly arise and how to check what applies to your business. - read more

Start Here !
Start here!
Cover Amount:
Postcode:

All quotes are provided obligation-free by a participating broker from our national referral partner network. We respect your Privacy.


Knowledgebase
Copayment:
A fixed amount you pay for a covered healthcare service, usually when you receive the service.