Severe Weather Readiness Starts With Practical Office Cover
Why SMEs should check sums insured before disruption strikes
The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Fresh insurance industry commentary ahead of the warmer months is again putting severe weather, repair costs and business interruption risk in front of Australian small businesses.
For office-based SMEs, the warning is not limited to flood-prone or coastal locations.
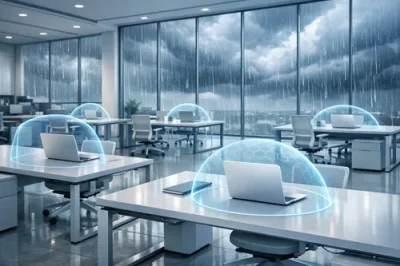
Storm damage, water ingress, power interruption, fallen trees, damaged signage and access restrictions can all affect a professional workplace, even when the premises itself appears relatively low risk.
The timing matters because many office insurance policies are renewed on autopilot. A business may have added workstations, upgraded technology, expanded into a larger tenancy or increased reliance on cloud systems since its last proper review. If sums insured remain based on old replacement values, a claim may expose an uncomfortable gap between what the business owns and what the policy is prepared to fund.
This is an extension of the recent discussion about easing commercial insurance conditions: more stable premiums are useful, but they do not remove the need for disciplined cover decisions. If market pressure eases slightly, SMEs should use that breathing space to improve accuracy rather than simply trimming limits to save money.
For an office tenant, the key areas to review usually include fit-out, furniture, computers, servers, phone systems, portable equipment, records, tenant improvements, glass, theft cover and business interruption. For an owner-occupier or commercial landlord, building reinstatement costs, professional fees, demolition, debris removal, compliance upgrades and loss of rent may also need attention.
A practical review should focus on the following questions:
Would the current contents and equipment limit replace assets at today’s prices, including delivery, installation and configuration?
Is the business interruption indemnity period long enough if repairs, approvals, supply delays or relocation take longer than expected?
Does the policy respond if the premises is not damaged but access is restricted, utilities fail or a key supplier is interrupted?
Are exclusions for flood, stormwater, wear and tear, maintenance or gradual damage clearly understood?
Have lease obligations, landlord requirements and client contracts changed since the policy was arranged?
Office operators should also document assets before an event occurs. Photos, invoices, asset registers, software licences and tenancy documents can make the claims process more efficient and reduce disagreement over value or ownership. Businesses that rely heavily on laptops and remote work should check whether equipment is covered away from the insured premises.
The broader lesson is simple: weather risk is becoming a continuity issue, not just a property issue. Before peak storm season, SMEs should estimate current replacement costs, review interruption assumptions and consider whether their office insurance coverage still reflects how the business actually operates. Tools that help estimate appropriate sums insured can provide a useful starting point before comparing policy options or seeking advice.
Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.
Australia's construction sector remains under pressure, with recent insolvency figures continuing to show building and construction as one of the most exposed parts of the economy. Higher material costs, tight margins, labour shortages, delayed payments and fixed-price contract stress have all contributed to a tougher operating environment for builders, subcontractors and project owners. - read more
Recent transport industry sales updates point to a more selective new-truck market, with operators weighing replacement timing against finance costs, emissions planning, availability and contract confidence. For truck businesses, that matters well beyond the showroom. A change in buying momentum can flow through to vehicle values, repair economics, insurer appetite and the way fleets should set insurance sums before renewal. - read more
Fresh small business cyber warnings are a practical reminder that digital risk is no longer just a concern for large companies with complex IT systems. For Australian tradespeople, the most damaging cyber incident may be far simpler: a fake invoice, altered bank details, a compromised email account or a scam message that looks like it came from a supplier, builder, real estate agent or client. - read more
ASIC’s continuing focus on superannuation member services has put another practical issue in front of Australian workers: insurance inside super is not just about whether cover exists, but whether members can understand and use it when they need help. Recent regulatory attention on trustee administration, communication and claims support is a timely reminder for anyone relying on salary continuance or income protection benefits through their fund. - read more
Professional indemnity and public liability insurance protect small businesses against different types of claims. Understanding the difference can help you assess whether your risks relate mainly to advice and professional services, physical injury and property damage, or both. - read more
Professional indemnity insurance stands as a pivotal safeguard for Australian professionals navigating the intricacies of liability in their work life. This form of insurance is designed to protect professionals against legal costs and claims for damages arising from acts, omissions, or breaches of professional duty in the course of their practice. Whether it's due to an honest mistake or an unforeseen error, the ramifications of such professional oversights can be financially crippling. - read more
Environmental liability can affect how Australian businesses plan projects, manage operations, train staff and arrange insurance. This guide explains the main types of environmental liability, the regulatory issues businesses may need to consider, and practical ways to manage environmental risks without treating insurance as a substitute for compliance. - read more
Welcome to the crucial world of risk management for Australian tradesmen. Whether you're a seasoned professional or just starting, understanding and mitigating the inherent risks in the trades industry is paramount to both the safety and sustainability of your business. This article intends to guide you through the world of risk management, emphasizing the pivotal role of liability insurance. - read more
Start Here !
Knowledgebase
Occupational Hazard: A risk associated with the nature of a particular occupation, which may affect insurance premiums.



No comments yet. Be the first to share your thoughts.