Liability Insurance :: News
SHARE

Share this news item!

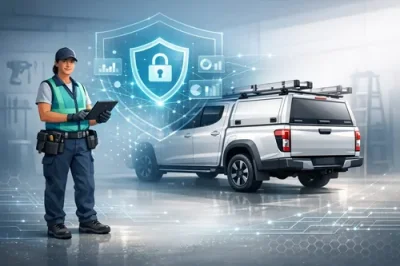
Cyber Scam Alerts: What Trade Businesses Should Check Now

Invoice fraud and email compromise can turn a routine job into a costly business setback

Cyber Scam Alerts: What Trade Businesses Should Check Now?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

Fresh small business cyber warnings are a practical reminder that digital risk is no longer just a concern for large companies with complex IT systems.
For Australian tradespeople, the most damaging cyber incident may be far simpler: a fake invoice, altered bank details, a compromised email account or a scam message that looks like it came from a supplier, builder, real estate agent or client.

That matters because many trade businesses now run on fast digital communication. Quotes are emailed from the ute, deposits are requested by text, progress claims are sent through accounting software, and supplier invoices are approved between jobs. If a criminal intercepts that process, money can move quickly and the recovery path can be difficult.

The insurance question is not just whether a business has a general policy. Many traditional covers are designed for physical loss, third-party injury or damage to property. Public liability insurance, for example, remains important for site-based risks, but it is not usually intended to fix every loss caused by email compromise, social engineering or fraudulent payment instructions.

Cyber cover, crime cover or specific extensions may respond in some situations, but the details matter. Some policies distinguish between computer hacking, funds transfer fraud, invoice manipulation and voluntary payments made after a deception. Others may require proof that security controls were in place, such as multi-factor authentication, password management, staff procedures and prompt notification after an incident.

Tradies should treat cyber risk as part of everyday business continuity planning, not as a separate technology issue. A stolen trailer can stop a job because tools and equipment are missing; a diverted payment can have the same effect if cash flow disappears just before wages, materials or vehicle costs are due.

Practical steps include confirming bank detail changes by phone using a known number, limiting who can approve payments, turning on multi-factor authentication, backing up important files, and keeping job records, invoices and client communications organised. These habits can reduce the chance of a claim and may also make it easier to show an insurer what happened if something goes wrong.

The key takeaway is simple: as trade businesses become more mobile and digital, insurance reviews need to move with them. A policy that suited a paper-based operation years ago may not reflect how quotes, invoices, bookings and payments are handled today.

Published:Thursday, 17th Sep 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Insurance News

Why rising builder failures matter for contract works cover
17 Sep 2026: Paige Estritori
Australia's construction sector remains under pressure, with recent insolvency figures continuing to show building and construction as one of the most exposed parts of the economy. Higher material costs, tight margins, labour shortages, delayed payments and fixed-price contract stress have all contributed to a tougher operating environment for builders, subcontractors and project owners. - read more
How Softer Truck Sales Can Affect Insurance Decisions
17 Sep 2026: Paige Estritori
Recent transport industry sales updates point to a more selective new-truck market, with operators weighing replacement timing against finance costs, emissions planning, availability and contract confidence. For truck businesses, that matters well beyond the showroom. A change in buying momentum can flow through to vehicle values, repair economics, insurer appetite and the way fleets should set insurance sums before renewal. - read more
Cyber Scam Alerts: What Trade Businesses Should Check Now
17 Sep 2026: Paige Estritori
Fresh small business cyber warnings are a practical reminder that digital risk is no longer just a concern for large companies with complex IT systems. For Australian tradespeople, the most damaging cyber incident may be far simpler: a fake invoice, altered bank details, a compromised email account or a scam message that looks like it came from a supplier, builder, real estate agent or client. - read more
Why Super Service Standards Matter for Your Income Protection
17 Sep 2026: Paige Estritori
ASIC’s continuing focus on superannuation member services has put another practical issue in front of Australian workers: insurance inside super is not just about whether cover exists, but whether members can understand and use it when they need help. Recent regulatory attention on trustee administration, communication and claims support is a timely reminder for anyone relying on salary continuance or income protection benefits through their fund. - read more


Business Insurance Articles

Product Liability Insurance in Australia: A Practical Guide for Business Owners
Product liability insurance can help protect Australian businesses from the financial impact of claims alleging that a product they manufactured, imported, distributed or sold caused injury, illness or property damage. This guide explains how the cover works, what to check in a policy and how it fits into broader product risk management. - read more
Public Liability Insurance Claims: What to Expect and How to Prepare
Public liability insurance can help protect a business when a third party alleges they were injured or their property was damaged because of the business's activities. If an incident occurs, knowing what to document, when to contact your insurer and how to communicate with others involved can make the claims process easier to manage. - read more
How to Assess Risk Exposure and Choose Professional Indemnity Cover
Professional indemnity insurance can help Australian professionals manage the financial impact of allegations involving mistakes, omissions, negligent advice or breaches of professional duty. Choosing cover starts with understanding your own risk exposure, then matching that exposure to policy limits, exclusions, claims conditions and continuity arrangements. - read more
Professional Indemnity vs Public Liability Insurance: Which Cover Does Your Small Business Need?
Professional indemnity and public liability insurance protect small businesses against different types of claims. Understanding the difference can help you assess whether your risks relate mainly to advice and professional services, physical injury and property damage, or both. - read more

Start Here !
Start here!
Cover Amount:
Postcode:

All quotes are provided obligation-free by a participating broker from our national referral partner network. We respect your Privacy.


Knowledgebase
Income Insurance:
Insures your income in the event of you being unable to work due to sickness or accident.