


Liability Insurance :: News
SHARE

Share this news item!

Rural Crime Concerns Put Farm Assets Back in the Spotlight

Why theft, trespass and record gaps can affect more than the immediate loss

Rural Crime Concerns Put Farm Assets Back in the Spotlight?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

Fresh regional reporting on rural crime has brought a familiar farm risk back into view: the loss of machinery, fuel, tools, livestock and stored inputs through theft or unauthorised access.
While weather and biosecurity often dominate farm risk discussions, crime can be just as disruptive when it stops work, delays contractors or leaves a producer without essential equipment at a critical point in the season.

For farm operators, the insurance issue is not only whether an item is stolen. It is whether the policy wording, asset records, security arrangements and claim evidence are strong enough to support a smooth outcome. A missing side-by-side, spray unit, generator or fuel tank can quickly become a business interruption problem if replacement parts are scarce, seasonal work is time-sensitive or the farm is relying on one key item of plant.

Rural crime also exposes the difference between owning an asset and being able to prove its value, condition and location. Insurers may ask for serial numbers, purchase records, photographs, service histories, livestock counts, identification records or proof of forced entry. Where equipment has been modified, shared between properties, left at a leased block or used by contractors, the detail matters. This is where setting realistic sums insured and keeping asset schedules current can reduce stress after a loss.

Livestock theft brings another layer of complexity. Electronic identification, movement records, paddock counts and saleyard documentation can all help establish ownership and quantity. For mixed farms, it is worth checking whether theft cover applies to livestock in all locations, including agistment, leased country, holding yards and transport situations. Policy exclusions and sub-limits can vary, especially where theft is not discovered immediately.

Practical steps worth reviewing now include:

  • Recording serial numbers and taking clear photos of machinery, tools, pumps, tanks and trailers.
  • Checking whether portable equipment, fuel, chemicals and fencing materials are listed adequately.
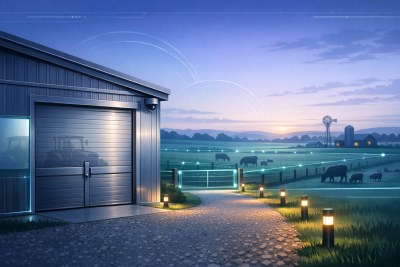
  • Reviewing gates, locks, lighting, cameras and visitor access points around sheds and yards.
  • Keeping livestock records, movement documents and paddock tallies up to date.

Insurance should sit alongside prevention, not replace it. Producers facing renewal should ask how their farm insurance cover responds to theft, malicious damage, trespass-related liability and temporary replacement costs. If the wording is unclear, a licensed broker can help compare exclusions, excesses and evidence requirements before a claim tests the policy.

Published:Wednesday, 16th Sep 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Insurance News

Rural Crime Concerns Put Farm Assets Back in the Spotlight
16 Sep 2026: Paige Estritori
Fresh regional reporting on rural crime has brought a familiar farm risk back into view: the loss of machinery, fuel, tools, livestock and stored inputs through theft or unauthorised access. While weather and biosecurity often dominate farm risk discussions, crime can be just as disruptive when it stops work, delays contractors or leaves a producer without essential equipment at a critical point in the season. - read more
Why SME Insurance Confidence Still Needs a Reality Check
16 Sep 2026: Paige Estritori
The latest SME insurance research from Vero is a useful reminder that confidence and preparedness are not always the same thing. Many Australian small and medium-sized businesses know insurance is essential, but the harder question is whether their current cover would respond as expected after a major loss, liability claim or interruption. - read more
Why Firmer Cattle Prices Should Trigger an Insurance Check
15 Sep 2026: Paige Estritori
Recent rural market reporting has pointed to firmer cattle values across parts of eastern Australia, with improved seasonal confidence, restocker demand and tighter supply helping support prices in a number of saleyards. For producers, stronger prices are welcome after a period of difficult seasonal and cost pressures. But there is also a quieter insurance issue sitting behind the market lift: if livestock values rise, the financial exposure carried by the farm may rise with them. - read more
Softer premiums do not remove the need for sharper cover checks
15 Sep 2026: Paige Estritori
Recent commercial insurance market commentary points to a more favourable pricing environment for many Australian business buyers, with competition returning in some lines after several years of tougher renewal conditions. For consultants, this is welcome news, but it should not be mistaken for a signal that professional risk has become simple or low-cost to insure. - read more


Business Insurance Articles

When Is Liability Insurance Required for Australian Businesses?
Liability insurance is not compulsory for every Australian business, but it may be required by law, licence conditions, contracts, leases, tenders, permits or client agreements. This guide explains where requirements commonly arise and how to check what applies to your business. - read more
Environmental Liability for Australian Businesses: Risks, Laws and Insurance Considerations
Environmental liability can affect how Australian businesses plan projects, manage operations, train staff and arrange insurance. This guide explains the main types of environmental liability, the regulatory issues businesses may need to consider, and practical ways to manage environmental risks without treating insurance as a substitute for compliance. - read more
How Insurance Helps Protect Small Business Assets
Small businesses face risks that can affect their premises, equipment, stock, cash flow and reputation. Insurance helps transfer some of the financial impact of unexpected events to an insurer, so a single incident is less likely to derail day-to-day operations. - read more
How to Assess Your Risk Exposure and Select the Right Indemnity Coverage
Professional indemnity insurance stands as a pivotal safeguard for Australian professionals navigating the intricacies of liability in their work life. This form of insurance is designed to protect professionals against legal costs and claims for damages arising from acts, omissions, or breaches of professional duty in the course of their practice. Whether it's due to an honest mistake or an unforeseen error, the ramifications of such professional oversights can be financially crippling. - read more


Start Here !
Start here!
Cover Amount:
Postcode:

All quotes are provided obligation-free by a participating broker from our national referral partner network. We respect your Privacy.


Knowledgebase
No-Fault Insurance:
A type of car insurance where your insurer pays for your damages regardless of who is at fault in an accident.