Why Battery Fire Risk Belongs on the Salon Insurance Checklist
Charging habits, equipment storage and documentation can all affect how well a beauty business is prepared
3
The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Recent Australian insurance and small business risk commentary has again highlighted lithium-ion battery fires as a practical hazard for workplaces that rely on rechargeable equipment.
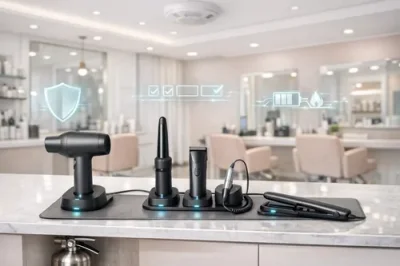
For beauty salons, skin clinics, nail studios and mobile beauticians, the issue is not limited to obvious items such as laptops or phones.
Many everyday tools, including cordless clippers, LED devices, payment terminals, tablets, portable speakers, torches and cleaning equipment, may depend on rechargeable batteries.
The risk for beauty businesses is twofold. First, a battery failure can create a sudden fire or smoke event that damages fit-out, stock, electronics and client areas. Secondly, even a contained incident can interrupt trading if the premises needs cleaning, electrical checks, replacement equipment or landlord approval before reopening. That makes battery safety relevant to contents cover, business interruption, lease obligations and broader risk management.
Insurers are increasingly interested in whether businesses can show sensible controls, not just whether a policy exists. For a salon, that may mean charging devices on non-flammable surfaces, avoiding overnight charging where possible, removing damaged batteries from service, using manufacturer-approved chargers, keeping heat sources away from charging areas and ensuring staff know what to do if a device swells, overheats or smells unusual.
Mobile beauticians face an additional layer of exposure because equipment is transported, charged in different locations and sometimes stored in vehicles between appointments. A battery damaged in transit may not show signs immediately, so it is worth checking cases, cords and devices as part of the normal setup and pack-down routine. If a tool is essential to daily income, its replacement value and downtime impact should also be considered.
The insurance takeaway is not to panic, but to update the risk picture. Salon owners should review whether their policy limits reflect current equipment, electronics, retail stock and fit-out values, and whether business interruption settings would be enough after a fire, smoke or electrical incident. Keeping purchase records, maintenance notes and photos of higher-value equipment can also help if a claim needs to be assessed.
This is also a useful prompt to revisit fire safety procedures, staff training and landlord requirements. Battery incidents may be small at first, but the resulting property damage and lost trading time can be significant for a service business with bookings, casual staff and regular clients.
As battery-powered devices become more common in beauty work, practical prevention and accurate sums insured should move together. If your equipment list has grown, your treatment mix has changed or you have added mobile services, take time to estimate practical insurance levels before your next renewal discussion.
Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.
Recent transport and fleet industry coverage continues to point to a steady increase in electric and low-emission heavy vehicles across Australian logistics operations. For many operators, the attraction is clear: quieter vehicles, lower tailpipe emissions, potential fuel savings and stronger alignment with customer sustainability targets. But the insurance conversation is now becoming more detailed than simply replacing a diesel truck with an electric one. - read more
APRA’s latest quarterly general insurance statistics point to a market that is still under cost pressure, even as insurers continue to report stronger overall results than during the worst of the recent claims cycle. For Australian tradespeople, the headline is not simply whether insurers are profitable. The practical issue is how rising premiums, repair costs, reinsurance expenses and claims activity flow through to the price and availability of cover used every day on the tools. - read more
Australia’s financial advice reform agenda has taken another important step, with industry attention turning to how simpler, more accessible guidance could help consumers make better decisions about insurance. For workers who rely on income insurance or salary continuance cover, the issue is more practical than political: many people hold cover they do not fully understand until illness or injury forces them to test it. - read more
Recent transport and insurance industry attention on lithium-ion battery safety is a timely warning for Australian truck operators. The issue is no longer limited to consumer products catching fire in homes or warehouses. Batteries now move through freight networks in tools, scooters, e-bikes, electronics, spare parts and energy storage equipment, and that creates a different risk profile for carriers, depots and subcontracted linehaul work. - read more
Professional indemnity insurance can help protect Australian professionals and service businesses against claims arising from alleged errors, omissions, negligence or breaches of professional duty. This guide explains what it may cover, how claims-made policies work and what to check before arranging cover. - read more
Choosing public liability insurance is not just about comparing premiums. Australian businesses should understand policy limits, exclusions, excesses, endorsements and conditions before deciding whether a policy is appropriate for their risks. - read more
Running a small business can be both rewarding and challenging. One of the key challenges is the variety of risks that can arise unexpectedly. These risks can range from financial uncertainties to operational hiccups, each potentially impacting your business's success. Understanding these risks and preparing for them is crucial for the longevity and sustainability of any small enterprise. - read more
Product liability insurance can help protect Australian businesses from the financial impact of claims alleging that a product they manufactured, imported, distributed or sold caused injury, illness or property damage. This guide explains how the cover works, what to check in a policy and how it fits into broader product risk management. - read more
Start Here !
Knowledgebase
Claim Adjuster: An insurance professional who investigates and evaluates insurance claims to determine the amount the insurance company should pay.








No comments yet. Be the first to share your thoughts.