Why Underinsurance Is Back on the Freelance Risk List
Replacement costs, client deadlines and cash flow need a fresh look
The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Recent insurance industry reporting has renewed attention on a familiar but often underestimated risk for small businesses: sums insured that no longer match the real cost of recovery.
For Australian freelancers, consultants and sole traders, this is not just a problem for shopfronts or factories.
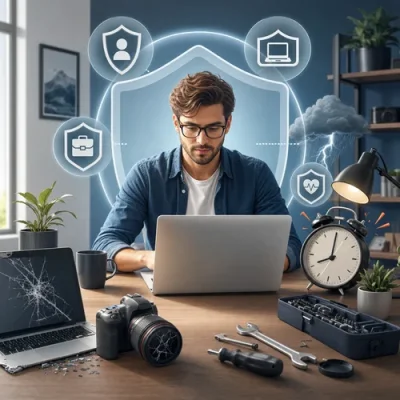
A laptop-based business can still rely on specialist equipment, software, a fitted-out home office, client records, portable tools, stock, or a studio space that would be expensive to replace quickly.
The concern is that inflation in repairs, replacement technology, building materials, labour and logistics can quietly outpace the figures listed on a policy schedule. A freelancer who set cover levels several years ago may assume they are protected, only to find that the insured amount falls short after theft, fire, storm damage or another insured event. That gap can become a direct cash flow problem at the worst possible moment.
Underinsurance also interacts with interruption risk. If a designer, photographer, consultant or trades-based contractor cannot work while equipment is replaced or a workspace is repaired, the issue is not only the cost of the damaged asset. It is also missed deadlines, lost billable hours and the potential strain on client relationships. That is where business interruption insurance may become relevant, particularly for freelancers whose income depends on specific tools, premises or project timelines.
A practical review does not need to be complicated, but it should be specific. Freelancers should avoid relying only on accounting book values, because depreciated figures may be far below today's replacement cost. Instead, consider what it would cost to buy equivalent equipment now, restore essential files or systems, replace furnishings, meet lease or studio obligations, and keep the business operating during a disruption.
Useful checkpoints include:
Reviewing policy schedules before renewal, not after a claim.
Checking whether portable equipment is covered away from the main premises.
Testing whether business interruption limits reflect current revenue and recovery time.
Keeping receipts, asset registers and photographs in secure cloud storage.
Confirming whether exclusions, sub-limits or excesses could reduce the expected payout.
The broader lesson is that affordability should not be measured by premium alone. A cheaper policy with outdated limits may leave a freelancer funding the difference personally. For self-employed Australians without paid leave or employer support, estimating replacement costs and interruption exposure is part of protecting both today's work and tomorrow's earning capacity.
Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.
Australia's construction sector remains under pressure, with recent insolvency figures continuing to show building and construction as one of the most exposed parts of the economy. Higher material costs, tight margins, labour shortages, delayed payments and fixed-price contract stress have all contributed to a tougher operating environment for builders, subcontractors and project owners. - read more
Recent transport industry sales updates point to a more selective new-truck market, with operators weighing replacement timing against finance costs, emissions planning, availability and contract confidence. For truck businesses, that matters well beyond the showroom. A change in buying momentum can flow through to vehicle values, repair economics, insurer appetite and the way fleets should set insurance sums before renewal. - read more
Fresh small business cyber warnings are a practical reminder that digital risk is no longer just a concern for large companies with complex IT systems. For Australian tradespeople, the most damaging cyber incident may be far simpler: a fake invoice, altered bank details, a compromised email account or a scam message that looks like it came from a supplier, builder, real estate agent or client. - read more
ASIC’s continuing focus on superannuation member services has put another practical issue in front of Australian workers: insurance inside super is not just about whether cover exists, but whether members can understand and use it when they need help. Recent regulatory attention on trustee administration, communication and claims support is a timely reminder for anyone relying on salary continuance or income protection benefits through their fund. - read more
Freelancers can face liability risks when providing services, visiting client sites or working with client property. Liability insurance can help manage the financial impact of certain claims, but the right cover depends on the type of work you do, your contracts and your risk exposure. - read more
Running a small business can be rewarding, but it also means dealing with risks that can affect cash flow, operations, customers and reputation. Understanding the main risk areas can help business owners plan ahead, reduce avoidable exposure and consider where insurance may fit within a broader risk management approach. - read more
Public liability insurance is designed to help protect a business when it is found legally responsible for injury or property damage suffered by a third party because of its operations. If an incident occurs, the quality of your documentation can make a major difference to how clearly the claim is assessed. - read more
Liability insurance helps Australian small businesses manage the financial impact of legal claims involving injury, property damage, negligent services or products connected with business activities. Understanding the main types of cover, policy limits, exclusions and claims processes can help business owners make more informed risk management decisions. - read more
Start Here !
Knowledgebase
Professional indemnity: An insurance that provides cover for liability incurred in the course of exercising a profession.



No comments yet. Be the first to share your thoughts.